Best Identity Theft Protection
A plain-English 2026 buying guide for families, seniors, and everyday buyers comparing Aura, LifeLock, IDShield, Identity Guard, and Experian IdentityWorks.
Quick Answer
Aura is the best identity theft protection service for most Sybari readers in 2026 because it bundles three-bureau monitoring, device security, and data broker removal in one subscription. LifeLock is the strongest alternative for buyers who want Norton-backed identity protection, while Experian IdentityWorks is the better fit for credit-first buyers who do not need a broad device-security bundle.
Official provider pages reviewed August 7, 2026
5 services compared
For families, seniors, and credit-focused buyers
Best identity theft protection services for most buyers
Aura
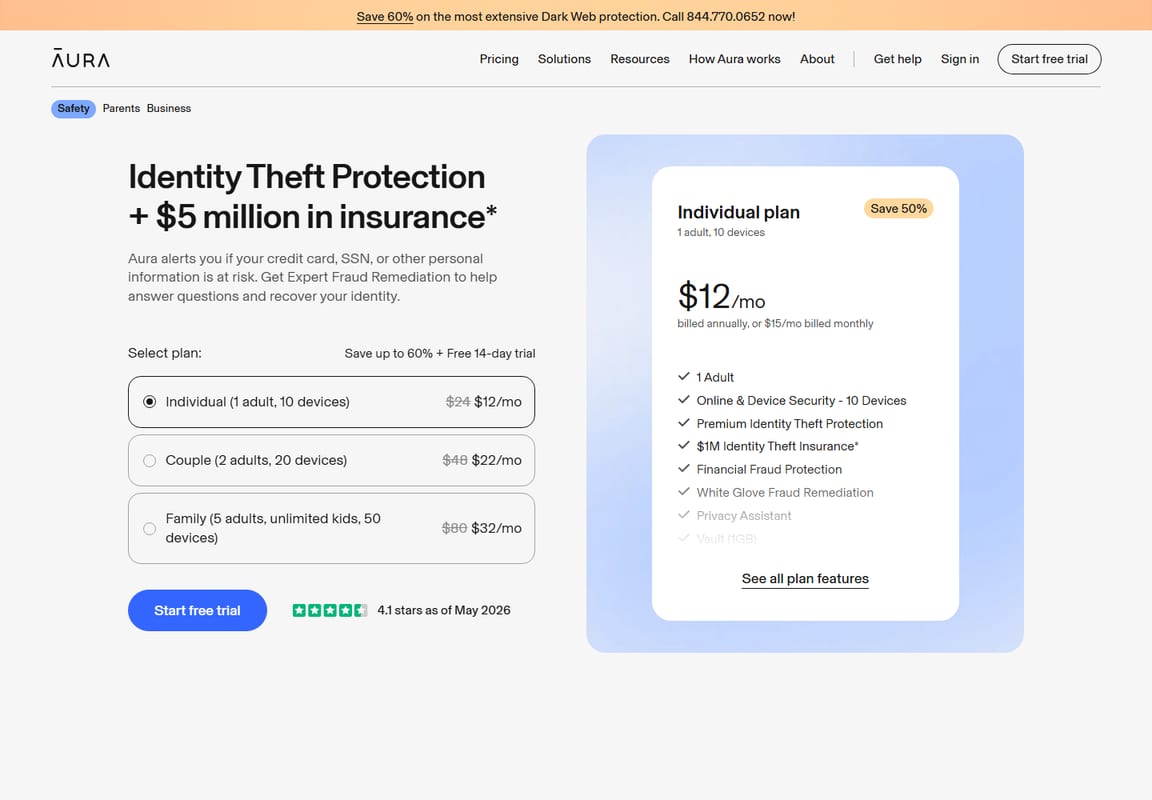
Official pricing page showed individual plans from $12/month billed annually on August 7, 2026.
Best for families and non-technical buyers who want identity monitoring, device security, and data broker removal in one bundle.
Strong fit if you will actually use the bundle.
Can feel expensive if you already pay for separate security tools.
LifeLock
Core annual pricing started at $10.42/month for the first year when checked on August 7, 2026.
Best for buyers already considering Norton’s ecosystem and who want more tiered reimbursement choices.
Strong plan ladder and broader reimbursement on upper tiers.
Comparing annual intro pricing against renewal pricing takes more work.
Experian IdentityWorks
Premium was listed at $24.99/month and Family at $34.99/month after the free trial on August 7, 2026.
Best for buyers who want credit-focused identity protection without paying for a large extra device-security bundle.
Good fit when credit monitoring is the main reason to pay.
Less attractive if you also want VPN, antivirus, or password-manager value.
Best identity theft protection comparison
| Service | Best for | Credit monitoring | Main strength | Main drawback |
|---|---|---|---|---|
| Aura | Families and all-in-one buyers | 3-bureau | Identity, device security, and data removal in one bundle | Less attractive if you only need a narrow identity product |
| LifeLock | Norton users and reimbursement-focused buyers | Tier-dependent, with 3-bureau on higher plans | Strong plan ladder and family options | Intro pricing and reimbursement terms take more comparison work |
| IDShield | Buyers who value restoration support | 1-bureau or 3-bureau depending on plan | Licensed private-investigator restoration model | Pricing rises quickly if you need 3-bureau monitoring |
| Identity Guard | Budget-conscious households | Higher tiers add broader monitoring | Lower-cost family entry point | Best features are not on the cheapest tier |
| Experian IdentityWorks | Credit-first buyers | Premium and Family tiers | Strong credit-centered experience and family option | Not built as a broad household security bundle |
Identity theft protection pricing notes
| Service | Official pricing snapshot checked August 7, 2026 | What to verify before paying |
|---|---|---|
| Aura | Individual from $12/month annually or $15/month monthly; couple and family tiers cost more. | Adult and child limits, device limits, renewal terms, and whether bundled tools overlap with what you already use. |
| LifeLock | Core from $10.42/month first-year annual billing, Advanced from $16.67, Total from $29.17 before renewal. | Reimbursement depth by tier, annual intro price versus renewal, and which family members get which benefits. |
| IDShield | Individual starts at $14.95/month for 1-bureau or $19.95/month for 3-bureau; family from $29.95 or $34.95. | Whether 1-bureau monitoring is enough, and whether the restoration model justifies the higher 3-bureau tier. |
| Identity Guard | Family entry pricing started around $14.99/month billed annually, with higher Total and Ultra tiers. | Which credit features and monitoring depth sit behind higher tiers. |
| Experian IdentityWorks | Premium at $24.99/month and Family at $34.99/month after the free trial. | Trial conversion terms, family limits, and whether you want a credit-focused service rather than a full bundle. |
Sybari buying rule
Never buy identity theft protection based on promo pricing alone. Compare renewal cost, monitoring depth, family coverage limits, restoration quality, and whether you already get similar tools free from your bank or another subscription.
What matters most when comparing identity theft protection
| Feature | Why it matters | Who should care most | Where to start |
|---|---|---|---|
| 3-bureau monitoring | A fraudulent account may appear on only one bureau first. | Anyone paying for serious credit monitoring | Aura, LifeLock higher tiers, Experian Premium, IDShield 3-bureau |
| Restoration support | Alerts matter less if the recovery help is weak. | Seniors, busy families, breach victims | IDShield, Aura, LifeLock |
| Family coverage rules | "Family" can mean two adults and children, or up to five adults plus children. | Parents, caregivers, multigenerational households | Aura, Identity Guard, LifeLock family plans |
| Data broker removal | Some identity plans also reduce people-search exposure. | Privacy-focused buyers | Aura, LifeLock current lineup, or compare dedicated removal tools |
| Bundle overlap | You may already have free credit monitoring or paid device security elsewhere. | Budget-conscious buyers | Check current bank, card, employer, and security subscriptions first |
Who should buy identity theft protection, and who should skip it?
| Choose a paid service if… | Skip or compare first if… | Better next step |
|---|---|---|
| You want alerts, restoration support, and one dashboard after a breach or fraud scare. | You only want basic credit monitoring. | Start with free bureau monitoring and credit freezes first. |
| You are buying for a family or older parent and want simpler setup. | You already pay for overlapping VPN, antivirus, or password tools. | Compare bundle overlap before adding Aura or LifeLock. |
| You want help if identity theft actually happens. | Your main issue is people-search exposure, not fraud alerts. | Compare The 7 Best Data Removal Services for 2026 or Best Data Removal Services for Seniors instead. |
| You are willing to pay for broader monitoring and support. | You are only responding to a promo discount. | Compare renewal pricing and what each tier actually includes. |
Common identity theft protection complaints
Renewal pricing feels much higher than the intro offer
This is one of the most common buyer complaints across identity-protection products. Always compare annual intro pricing with what the service says it will renew at.
Family plans are not directly comparable
Some services cover more adults, others more children, and some give better monitoring depth only to adults. Do not assume the cheapest family plan is the best value.
Buyers confuse insurance with stolen-money recovery
Identity theft insurance often covers recovery expenses, not every direct financial loss. Read the policy details before relying on the headline number.
What to do before paying for identity theft protection
- Freeze your credit with Equifax, Experian, and TransUnion.
- Set up free monitoring through your bank, card issuer, or free bureau tools.
- Secure your email with a strong password and MFA because email is the recovery hub for most accounts.
- Check your existing subscriptions for overlap, especially if you already pay for security software or privacy tools.
- Decide your real need between credit alerts, restoration support, family simplicity, or data broker removal.
Protecting family accounts and work accounts at the same time?
Start with a plain-English plan
If you are choosing identity protection for a household and also worry about business email, Microsoft 365, or account recovery risk, use Sybari’s broader planning guides before you buy overlapping subscriptions.
What Sybari would do first
Start with free credit freezes and free monitoring. If you still want a paid identity-protection service, compare Aura first for all-in-one household coverage, LifeLock if you want a strong mainstream alternative, and Experian IdentityWorks if your decision is mostly about credit monitoring.
If privacy removal matters as much as fraud alerts, compare dedicated services too. Paying for the wrong bundle is a more common mistake than skipping protection entirely.
About the Reviewer
Reviewed by David Durden
Cybersecurity Analyst and Senior Reviewer at Sybari
David reviews cybersecurity tools, privacy products, and online safety software for non-technical buyers. Sybari focuses on source-backed buying guidance, clear tradeoffs, and practical advice about what to buy, what to skip, and what to verify before paying.
Keep comparing before you buy
Sources and product pages reviewed
Consumer protection sources
Product pages reviewed
How we reviewed identity theft protection services
What we checked
We reviewed official pricing pages, plan-comparison pages, support pages, family-coverage language, reimbursement or insurance summaries, and FTC recovery guidance on August 7, 2026. We focused on monitoring depth, family plan meaning, recovery support, data-removal overlap, and renewal-risk questions.
What we did not test
We did not run a Sybari-controlled fraud case, simulate claim payouts, test alert speed across each service, or verify every restoration workflow firsthand. This page should not claim hands-on testing unless future lab notes or screenshots are added.
Best identity theft protection FAQ
What is the best identity theft protection service for most people?
Aura is the best overall starting point for most Sybari readers because it combines monitoring, device security, and data broker removal in one bundle. LifeLock is the main alternative, and Experian IdentityWorks is better for buyers who mainly care about credit.
Is identity theft protection worth paying for?
It can be worth paying for if you want broader monitoring, restoration support, or simpler family setup after you already used free credit freezes and free monitoring. It is less compelling if your only need is a basic credit alert.
What does identity theft protection not cover?
It does not stop every scam, breach, or fraudulent attempt. Policy terms also vary, so a headline reimbursement number does not mean every direct loss is covered.
Should families buy Aura or LifeLock?
Families should compare how many adults and children each plan covers, what monitoring depth each family member gets, and whether the bundled device tools matter. Aura is usually the simpler all-in-one choice. LifeLock is stronger if you prefer Norton’s ecosystem and want to compare more tiered reimbursement options.
Can you set up enough protection for free?
Partly, yes. Free credit freezes and free monitoring tools cover the basics. Paid services mainly add broader alerts, restoration support, family simplicity, and in some cases device or privacy features.